
After an accident, putting losses into writing can feel like one more burden during a difficult time. A personal injury settlement demand letter Missouri claimants send to an insurer is a structured explanation of what happened, how injuries affected them, and what evidence supports their request. It should connect the incident to the injury and the injury to documented losses, not simply name a dollar figure.
Discuss your injury claim with an attorney
This guide explains the usual parts of a demand, how to organize supporting records, and what to consider before sending one or accepting a proposed settlement. A demand does not guarantee payment. An insurer may dispute responsibility, whether treatment relates to the incident, the amount of a loss, or the terms needed to resolve a claim. The right timing and approach depend on the facts.
What does a personal injury demand letter do?
A demand letter presents a claimant’s position to the responsible party or insurer. It normally identifies the incident, summarizes injuries and treatment, describes the losses being claimed, and asks for a particular resolution. Documents attached to the letter help the reader check the facts and calculations.
Think of the letter as a roadmap through the evidence. A clear chronology can explain how a collision occurred, when symptoms began, what care followed, and how the effects changed over time. An indexed packet is generally easier to evaluate than a stack of unrelated records. The goal is clarity and accuracy, not dramatic language.
A demand is not a court filing. Sending one does not start a lawsuit, establish that the other party is liable, or stop a legal deadline from running. If your injury followed a truck collision, the facts may involve additional parties or records; the firm’s guide to Missouri truck accident claims discusses some of those issues. A lawyer can assess which matters apply to a particular claim.
When should you prepare a demand?
Timing is a balance. A demand sent before the injury picture is reasonably clear may omit treatment, restrictions, or expenses that later become important. Yet waiting without tracking deadlines can create a different risk. Medical recovery has no fixed timetable, and there is no single date that fits every claim.
Before deciding whether the claim is ready for a demand, check whether you can answer these questions:
- Have you collected the incident information, photographs, witness details, and any available report?
- Do you have the records and itemized bills for the treatment being included?
- Are treatment recommendations, current symptoms, and work restrictions documented?
- Can you describe missed work and other claimed expenses with dates and supporting records?
- Have you identified the relevant insurer, claim reference, and potentially responsible parties?
- Have you separately confirmed the legal deadline that may apply?
Missouri generally has a five-year limitations period for many personal injury actions, but exceptions and different rules can apply. The deadline may turn on the claim type, parties, and circumstances. Do not treat a general statement as a case-specific calculation or assume that insurer discussions extend a filing deadline. For official court information and resources, consult the Missouri Courts website; the applicable limitations rule should still be checked for the specific claim.
What should the letter include?
A useful demand is factual, organized, and tied to supporting material. The exact format varies, but these elements give the reader a consistent path through the claim.
- Claim identification. State the injured person’s name, date and location of the incident, the insured or other party, and the claim or policy reference if known. Include a reliable way for the adjuster to respond.
- Incident chronology. Explain the sequence of events in plain language. Distinguish what you personally observed from what another person reported. Do not guess about speed, distance, or anyone’s intent.
- Basis for responsibility. Describe the conduct or condition you believe caused the incident and identify evidence that bears on it. If fault is disputed or a fact remains uncertain, acknowledge that rather than presenting an assumption as settled.
- Injuries and care. Summarize symptoms, diagnoses, treatment dates, providers, and recommendations. Explain what has improved and what remains unresolved, using records to support the account.
- Financial losses. List documented medical charges, wage loss, and other relevant out-of-pocket expenses. Explain the arithmetic and cite the corresponding attachment or record.
- Everyday effects. Give concrete examples of how the injury changed ordinary activities, sleep, mobility, family responsibilities, or recreation. Specific, truthful details are more useful than broad conclusions.
- Requested resolution. State the amount or other resolution sought and explain what claim the request is intended to address. If you propose a response date, make it reasonable and appropriate; a date in a letter does not change legal deadlines.
- Attachment index. Number or label the supporting documents and use those labels in the text. The adjuster should be able to find a cited bill or photograph without searching the entire packet.
Send copies rather than irreplaceable originals, and keep a complete copy of the letter and attachments. Preserve delivery confirmation and later correspondence. If an insurer asks for records or a medical authorization, read the scope and duration carefully before signing. An authorization can permit access beyond the documents you intended to share.
How can you organize the evidence?
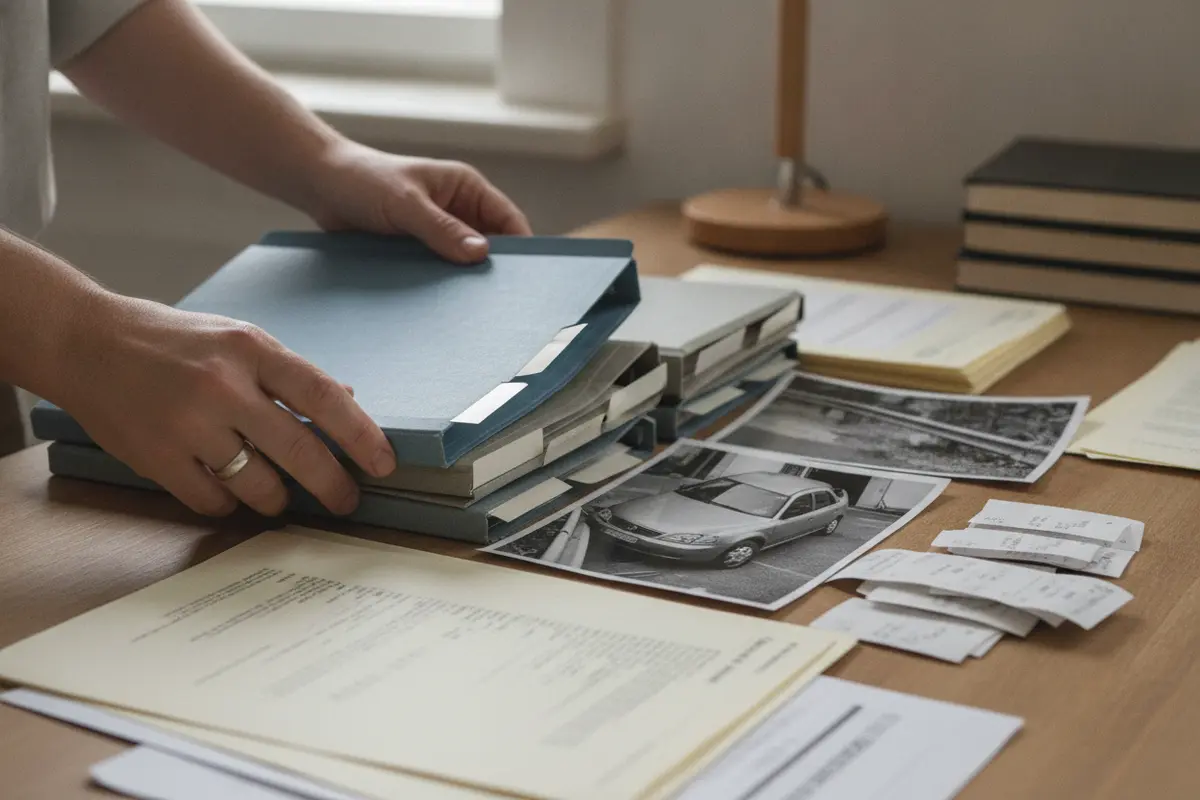
Organization helps the letter remain verifiable. Keep a master timeline with the incident, first symptoms, appointments, missed work, and important communications. Then make separate groups for the evidence. Avoid sending the same document several times under different labels.
- Incident materials: report information, photographs of the scene and damage, witness names and contact details, and relevant messages.
- Medical materials: records from relevant providers, itemized bills, prescriptions, referral information, and written restrictions or recommendations.
- Income materials: employer verification, pay documentation, dates absent, and an explanation of how any claimed reduction was calculated.
- Daily impact notes: dated observations about symptoms and limitations. Keep the account truthful and consistent with what you told providers.
- Claim communications: insurer letters, claim references, and a call log with dates, names, and the main points discussed.
A practical index might read: “A—incident report; B—scene photographs; C—emergency visit record; D—follow-up records; E—itemized bills; F—employer verification.” If a document has not arrived, mark it as outstanding rather than suggesting that it is included. Preserve the original digital files where possible, since they may contain useful date or source information.
Before sending medical information, consider whether each record is relevant to the injuries and losses in the claim. A new authorization may reach records beyond a particular visit or condition. Ask what it permits and why the information is requested. For help organizing incident information before a legal discussion, the firm’s personal injury questionnaire may provide a starting point.
How should you present losses without overstating them?
Make the arithmetic easy to follow. For each financial item, identify the period, amount, and supporting record. Medical charges should match the bills being submitted. Wage loss should show the dates missed and how the total was calculated. If care is ongoing or a future expense is uncertain, state that clearly rather than treating an estimate as an established bill.
| Claim item | Records that may help explain it | Accuracy check |
|---|---|---|
| Medical care | Relevant provider records and itemized bills | Check dates, services, and whether records concern the injury at issue |
| Lost income | Employer statement, pay records, and missed-work dates | Show the calculation and distinguish time missed from reduced earnings |
| Ongoing or future care | Provider recommendations and documented restrictions | Separate confirmed care from possible or unconfirmed treatment |
| Other expenses | Receipts and records showing the expense and date | Explain why the cost relates to the incident and avoid duplicate entries |
| Effects on daily life | Consistent treatment notes and dated personal observations | Describe concrete changes without exaggeration or unsupported conclusions |
The table is an organizing tool, not a formula for valuing a case. A total of medical bills does not automatically determine a settlement. Liability, the evidence, the nature and duration of injury, available coverage, and applicable rules can all affect evaluation. For a separate discussion of how settlement figures may be considered, see the firm’s article on motor vehicle accident claims; it should not be read as a promise of any particular amount.
How can Missouri fault rules affect a demand?
Missouri follows a pure comparative fault approach. In general, a claimant’s recovery can be reduced according to the claimant’s share of fault, rather than automatically barred simply because the claimant contributed to the incident. The parties may disagree about the evidence or the allocation. A demand should present known facts fairly and avoid claiming certainty where the record is incomplete.
For example, suppose accounts differ about whether a driver had time to stop and photographs show the vehicles only after impact. The letter can identify the conflicting accounts, describe the photographs, and note what evidence is still being sought. It is better to explain the limits of the present record than to invent a detail to fill a gap. The firm’s information on Missouri comparative negligence provides additional background, but a lawyer must evaluate how fault law applies to the evidence in an individual case.
Missouri does not generally impose a statutory cap on ordinary compensatory damages in most personal injury cases, but specific claim types and legal rules can differ. That broad point is not a valuation method or assurance of recovery. The practical task in a demand is to document the injury and losses and to explain the evidence on responsibility, not to rely on a slogan about what a claim should be worth.
What may an insurer look for?
An adjuster may review responsibility, the timeline of symptoms and care, whether treatment appears related to the event, the documentation for claimed losses, and applicable insurance terms. The insurer may ask for more records, dispute an item, or respond with a different settlement position. A request for additional information is not, by itself, acceptance or denial.
Chad Mann’s prior work with major national insurance carriers informs the firm’s understanding of how insurers evaluate, negotiate, and deny claims. That background can help anticipate questions an adjuster may raise, but it cannot predict or guarantee a particular response. Keep written communications measured and accurate. If you do not know an answer, do not guess; check the record first.
Take care before giving a recorded statement, signing a broad medical authorization, or accepting a release. A release may resolve claims more broadly than one bill or one stage of treatment. Read the full proposed document, including what claims and parties it covers, what payment it addresses, and whether it imposes other obligations. Get legal advice if its scope or effect is unclear. The firm’s guide to signs an injury claim may need an attorney offers context for deciding when to ask for help.
What common mistakes should you avoid?
- Sending an incomplete story. A rushed timeline may leave unexplained gaps between the incident, symptoms, and care. Add the dates and explain what is known.
- Using totals with no calculation. A figure is easier to assess when the letter shows its source and method.
- Guessing or exaggerating. Inconsistency can distract from well-supported facts and make clarification harder.
- Ignoring an unfavorable fact. If a fact is known and relevant, consider how to address it accurately instead of leaving an obvious gap.
- Sending an unindexed packet. Labels and attachment references help prevent confusion about which record supports which statement.
- Assuming negotiation protects a deadline. Track any applicable filing deadline separately and seek advice about it.
- Signing before understanding the release. The document may settle more than the immediate payment or expense under discussion.
These checks are especially important when injuries are serious, responsibility is disputed, or treatment is continuing. A personal injury lawyer can assess whether the letter accurately describes the available evidence and whether the proposed terms resolve the claims you intend to settle. You can also review the firm’s Missouri car accident claim information if the incident involved a motor vehicle.
What steps should you take before sending the letter?
- Build a dated timeline. Include the incident, symptoms, treatment, missed work, and important insurer communications.
- Collect the records. Gather relevant bills, provider records, wage support, photographs, and correspondence. List anything still outstanding.
- Check names and claim details. Confirm spelling, dates, claim references, and the correct delivery method.
- Match each statement to evidence. For every amount or factual assertion, identify the supporting document or explain what remains uncertain.
- Review for consistency. Check the letter against records and previous communications. Correct arithmetic errors and remove speculation.
- Keep a complete copy. Save the final letter, attachments, delivery confirmation, and any response. Record future dates and requests.
- Review settlement terms before acceptance. Do not focus on the payment alone; read what the release says it resolves.
When there are competing accounts, substantial injuries, future-care questions, or a possible deadline, legal guidance can help assess the specific issues. The firm’s discussion of when to get legal help after a crash explains why even an apparently small collision may call for closer review in some situations. General information cannot replace advice based on the complete facts.
Contact the Law Office of Chad G. Mann
Frequently asked questions
Does a demand letter require the insurer to pay?
No. It presents a claimant’s account, request, and supporting evidence. The insurer can investigate, dispute responsibility or losses, ask for more information, or negotiate. Sending a letter does not guarantee a settlement.
Should I include every medical record I have?
Not automatically. Focus on relevant records and understand the scope of any authorization before signing. If the insurer asks for broader information, consider what it covers and seek legal advice if you are unsure whether the request is appropriate.
Can I send a demand while treatment is ongoing?
It may be possible, but ongoing care can leave the duration, future needs, and full effects uncertain. Before resolving a claim, consider what remains unknown and whether a release would close claims beyond the expenses already documented.
Will the insurer offer the amount requested?
Not necessarily. The insurer may assess liability, documentation, coverage, and losses differently. Offers may be disputed or negotiated, and no particular result or amount can be promised.
A strong demand is clear about what is known, careful about what remains uncertain, and supported by organized records. Protect deadlines independently, review settlement terms closely, and seek advice when the facts or consequences are not clear.